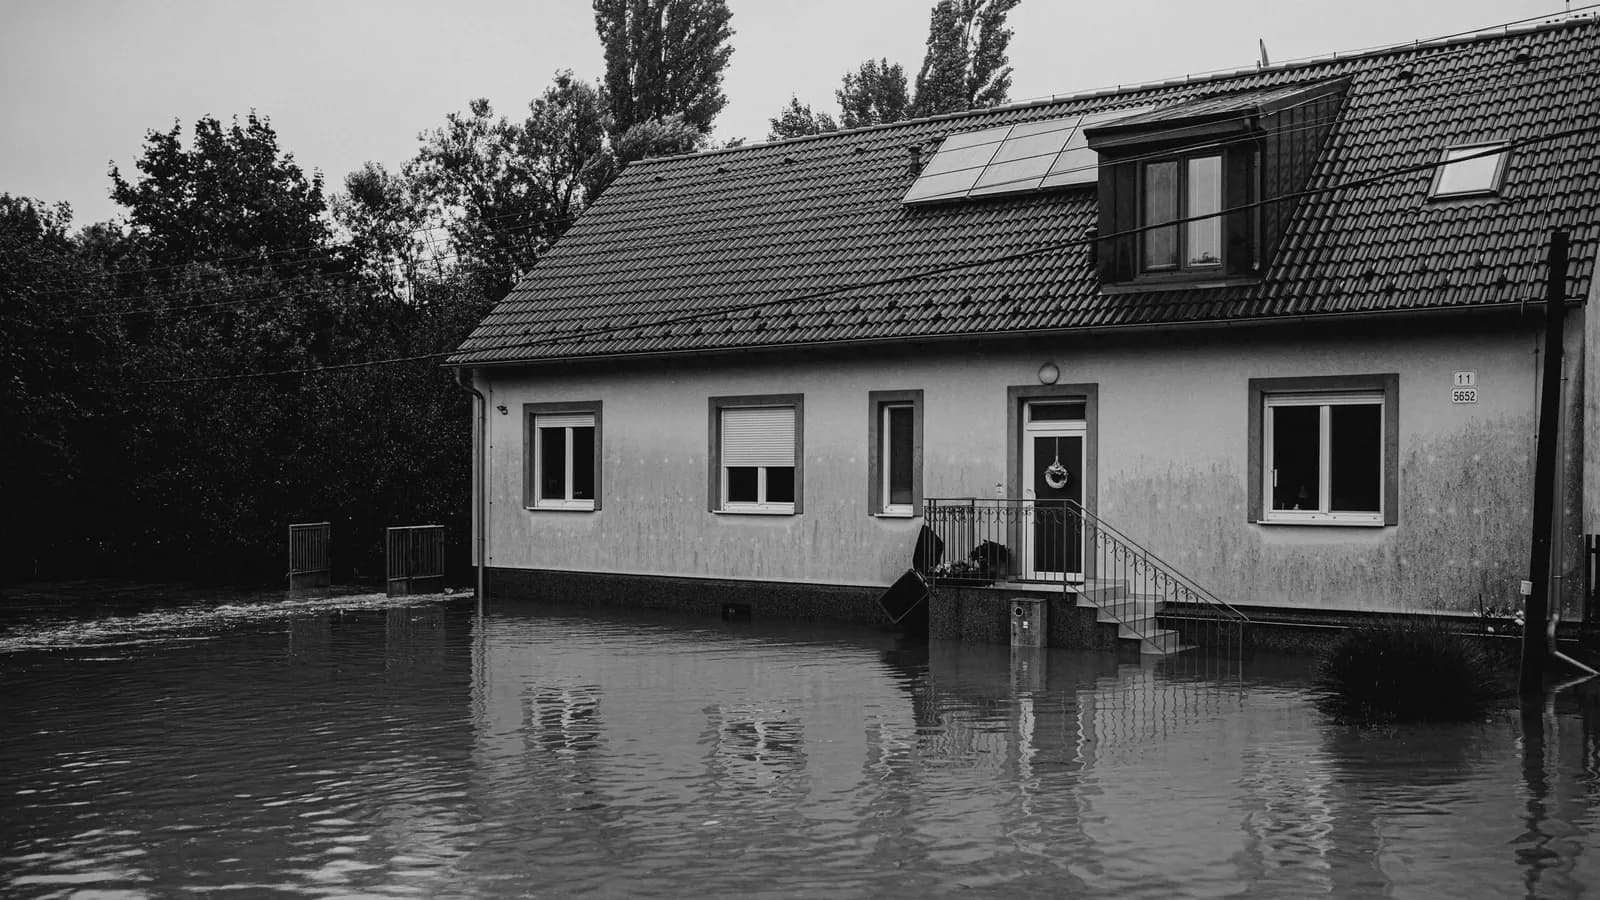
You need a flood risk assessment for a house extension in London if the house is in Flood Zone 2 or 3, or if it is in Flood Zone 1 and the land has critical drainage problems or shows as at risk of surface water flooding. Where one is needed, ours is from £375, and most London houses on higher ground need none at all.
On this page
The size of the extension does not decide it. A small single-storey kitchen extension in Flood Zone 3 needs an assessment; a large two-storey one in Flood Zone 1 on dry ground usually does not.
Does a small extension really count?
Yes. National policy says a site-specific flood risk assessment should accompany all development proposals in Flood Zones 2, 3a and 3b (NPPF chapter 18), and the planning guidance adds that applications for minor development involving extensions or additions should still meet the requirements (planning practice guidance).
What size changes is how long the document is. For a householder extension it follows a set method and runs to a few pages, not a hydraulic study.
There is one honest way out. If the extension is permitted development, there is no planning application, so there is nothing for an assessment to go with. Run the permitted development checker before you pay for any report.
How do I find my flood zone?
Put your postcode into the Environment Agency's flood map for planning, draw round the house and garden, and read the zone. It takes a few minutes.
Zone 1 means a low chance of flooding from rivers and the sea, Zone 2 a medium chance and Zone 3 a high one. Your council's strategic flood risk assessment splits Zone 3 into 3a and 3b, the functional floodplain. In London the higher zones follow the Thames and the rivers that feed it, so two houses a few streets apart can sit in different zones. Save the printout the service gives you: in Zone 1 with no other risk, it is the evidence that flood risk was looked at.
Can a house in Flood Zone 1 still need one?
Sometimes, and this is the case homeowners miss. The river zones only map rivers and the sea. Rain that cannot drain away floods houses too, so national policy also asks for an assessment in Flood Zone 1 on land the Environment Agency has identified as having critical drainage problems, or land the flood map or the council's strategic assessment shows at risk now or in the future (NPPF chapter 18).
In practice that tends to be a house at the dip in a road, over an old buried stream, or in a street where water already pools after heavy rain. When we check an address we read the surface water layer as well as the river zones. If surface water is the only risk, the assessment is about keeping water out of the new floor and away from the walls, not about river levels.
A council can also add its own requirement through its validation list. Our constraints check reads the flood layers with the other designations for your address in one go.
Do I need the sequential test as well?
No. The sequential test asks whether a scheme could go on another site at lower flood risk. That makes sense for new housing and makes none for an extension, because your extension can only go on your house. National policy lists householder development among the cases that do not need the test (NPPF policy F5).
The exemption stops at the house. A new self-contained home in the garden is not householder development, and in Flood Zone 2 or 3 it does need the test. We write that separately as a sequential test, and we tell you at the first check which of the two your scheme needs.
What does the assessment have to show?
For a householder extension of no more than 250 square metres, the Environment Agency does not comment on each case. It publishes standing advice for minor extensions, and the council checks the assessment against it (standing advice). Nearly every London extension is under that size.
The main test is the floor level. The advice asks for floors at least 600mm above the estimated flood level, or 300mm where that level is known with high certainty. An extension that has to meet the existing kitchen floor often cannot rise that far, and then the assessment sets out flood-resistant and flood-resilient construction instead. Our flood risk assessment cost guide walks through those levels in detail and what changes the price.
Is it the same as a drainage or SuDS statement?
No, they answer two different questions. The flood risk assessment asks whether the extension is safe from flooding and does not make it worse elsewhere. A drainage or SuDS statement asks where the rain falling on the new roof and paving goes: a soakaway, a water butt, permeable paving or the sewer.
A householder extension in a flood zone nearly always needs the first. Whether it needs the second depends on your council and how much hard surface you add. Where it helps, our assessment includes a short drainage note; where the council asks for a full one, our SuDS statement covers it. A basement is a different case again, with its own basement flood risk assessment.
What happens if I leave it out?
In Flood Zone 2 or 3 the council will usually not validate the application until the assessment arrives, so the decision clock does not start. If it gets through validation without one, the officer can still refuse on flood grounds because nothing shows the scheme is safe. Neither ends the project, but both cost weeks. The cheaper route is to check the zone while the planning drawings are being prepared, so the plans and the assessment go in together and agree on the floor level.
Frequently asked questions
My house is in Flood Zone 1. Can I ignore flood risk? Usually, yes. Check the surface water layer on the flood map and your council's validation list first; if neither flags the site, keep the map printout with your application.
Does a loft conversion need a flood risk assessment? Only if it needs planning permission and the house is in Flood Zone 2 or 3, or in Flood Zone 1 on land flagged for critical drainage or flood risk. Even then it is very short, because no new floor is added at ground level, and many loft conversions are permitted development with no application at all.
Can I write the assessment myself? For a simple extension you can, using the standing advice. The parts people get wrong are the estimated flood level and its source, and floor levels that do not match the drawings.
How much does yours cost? from £375 for a householder extension, quoted after a check that you need one.